Life Insurance Quotes
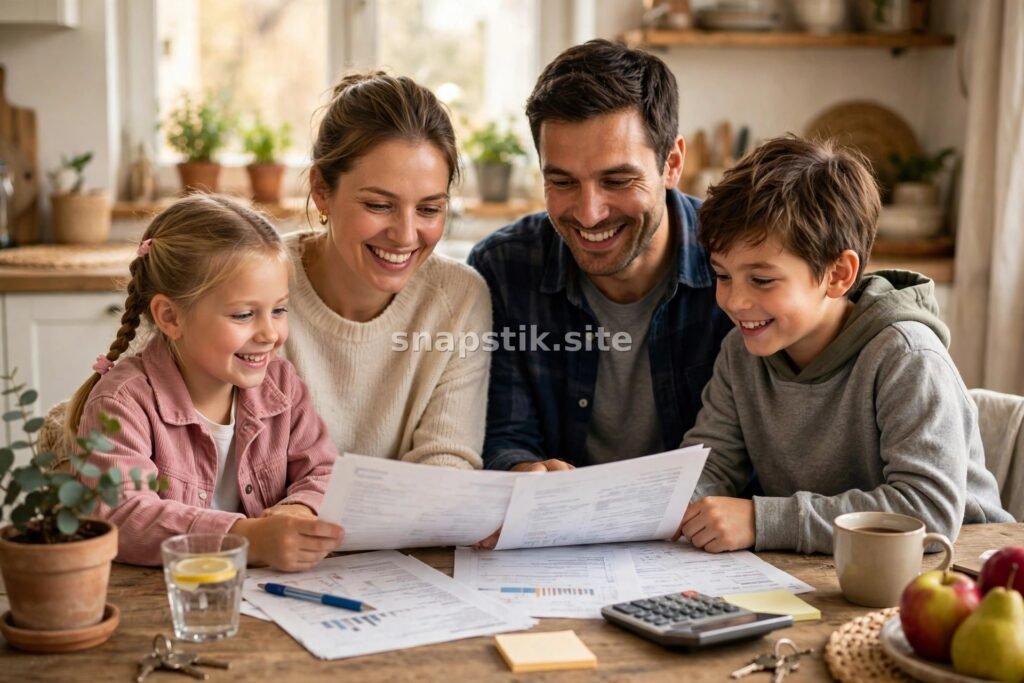
Life insurance is one of the kindest financial decisions a person can make for the people they love. It provides a payout to your chosen beneficiaries if you pass away, helping them cover living costs, debts, and future plans at a time when they need support most. Yet many people put it off, unsure where to start or how much cover they need.
Comparing life insurance quotes is the simplest way to begin. A quote shows you what a policy could cost and what it would provide, and comparing several quotes helps you find cover that fits your budget. This guide explains the main types of life insurance, how quotes work, what affects the cost, and how to choose a policy with confidence.
Why Life Insurance Matters
If other people depend on your income, life insurance helps protect them. The payout can replace lost income, pay off a mortgage or other debts, fund a child’s education, or simply give your family breathing room while they adjust.
Term Life vs Whole Life Insurance
The two most common types of life insurance are term life and whole life. Term life insurance covers you for a set period, such as ten, twenty, or thirty years. If you pass away during that term, your beneficiaries receive the payout. If the term ends while you are still alive, the cover simply stops. Term policies are usually the more affordable option and are a popular choice for covering a mortgage or the years when children are young.
Whole life insurance covers you for your entire life and usually includes a cash value component that grows slowly over time. It tends to cost more than term cover, but it never expires as long as premiums are paid, and some people value the savings element.
How Life Insurance Quotes Work
A life insurance quote is an estimate of what you would pay for a particular policy. To produce a quote, insurers usually ask for your age, health history, lifestyle, occupation, the amount of cover you want, and the length of the policy. Some quotes are instant estimates, while others require a fuller application and, in some cases, a medical exam.
Comparing quotes from several insurers is important because prices for similar cover can vary noticeably. Look beyond the monthly premium and check the cover amount, the term length, any exclusions, and whether the premium stays fixed or can rise over time. The cheapest quote is not always the best value if it comes with weaker terms.
What Affects the Cost of Life Insurance?
Several factors shape the price of a policy. Age is one of the biggest: younger applicants usually pay less because they are statistically less likely to claim soon. Health matters too, including your medical history, weight, blood pressure, and whether you smoke.
Your lifestyle and job can also play a role. Dangerous hobbies or high-risk occupations may raise the cost, while a healthy lifestyle can work in your favour. The amount of cover and the length of the term matter as well: more cover and longer terms generally mean higher premiums.
How Much Cover Do You Need?
There is no single right answer, but a useful starting point is to think about what your family would need without your income. Consider your outstanding debts, including a mortgage, everyday living costs for several years, childcare and education expenses, and final costs such as funeral expenses.
Tips for Comparing Quotes
- Compare like with like: same cover amount, same term, same type of policy.
- Check whether premiums are fixed or can increase over time.
- Read the exclusions and any waiting periods before you decide.
- Look at the insurer’s reputation for paying claims and customer service.
- Review your cover every few years or after big life changes, such as marriage, a new child, or buying a home.
Protecting your family is about more than one policy. Many households review their cover together, comparing home insurance quotes for the house itself and auto insurance quotes for the family cars, so that the whole household is covered. If you have been injured and are thinking about your family’s financial safety net, a personal injury attorney can also advise you on claims that may help with recovery costs.
This article is general information, not financial advice. Life insurance needs vary widely, so consider speaking with a licensed adviser about your own circumstances before choosing a policy.

CRM Software for Small Business
Water Damage Restoration: Steps to Take After a Leak or Flood

Private Health Insurance: A Beginner’s Guide to Choosing a Plan
About The Author

Beauty Hub
Beauty Hub is a small independent website sharing practical, honest guides on nails, beauty, skincare, fashion, watches, cakes and home decor — plus plain-English guides to everyday money topics. Everything here is researched and written by our own team, with images created by us for each article.